Money basics and budgeting: where your money goes and how to direct it
5 min read · Beginner
Every money decision sits on one simple equation: what comes in, minus what goes out, equals what you can keep. Budgeting is just the habit of deciding that equation on purpose instead of discovering it at the end of the month.
The three numbers that matter
Income is the money you actually receive after taxes and deductions - your take-home pay, not your salary. Expenses are everything that leaves your accounts, from rent to a streaming subscription. Cash flow is the difference between the two over a period, usually a month.
Positive cash flow means you have room to save, pay down debt or invest. Negative cash flow means you are covering the gap with savings or credit, which cannot last forever. Knowing which side you are on is the first and most useful money fact you can have.
Needs vs. wants
A need is something you would have to replace quickly if it disappeared: housing, utilities, groceries, basic transport, insurance and minimum debt payments. A want improves life but could pause without real harm: dining out, upgrades, hobbies, most subscriptions.
The line is personal and it moves. A car can be a need for a commute and a want when it is the premium trim. The point is not guilt - it is knowing which costs are fixed commitments and which are choices you can adjust when money is tight.
A simple starting budget: 50/30/20
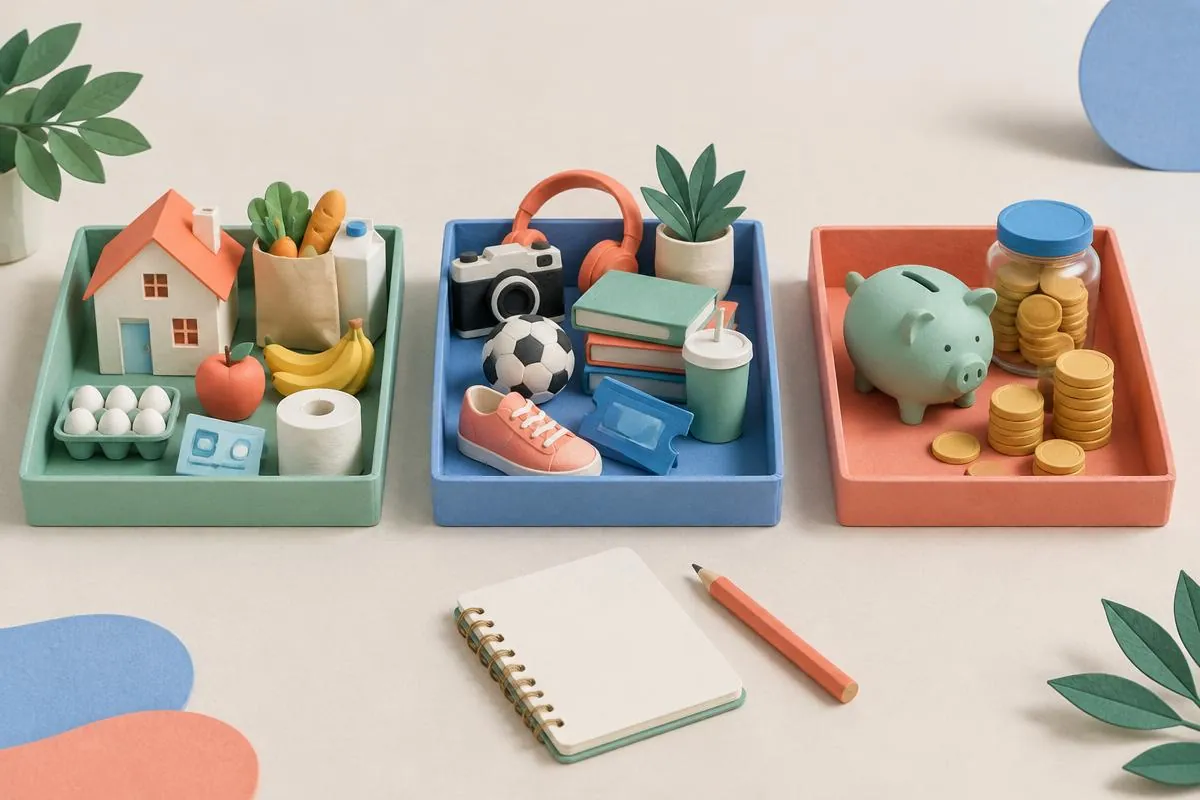
The 50/30/20 rule splits take-home pay into roughly 50% for needs, 30% for wants and 20% for savings and extra debt payments. It is a starting point, not a law. In high-cost areas needs often take more than half; that is normal, and the useful move is to adjust the other two shares deliberately.
- Zero-based budgeting gives every dollar a job until income minus planned spending equals zero.
- Envelope budgeting sets a fixed amount per category and stops when the envelope is empty.
- Pay-yourself-first moves savings out on payday and lets you spend the rest freely.
Smart spending without a spreadsheet obsession
Most overspending is not one big purchase; it is small recurring charges and convenience costs that quietly add up. Review recurring charges every few months, wait 24-48 hours before non-essential purchases above an amount you choose, and compare the cost of an item to the hours of work it represents.
Tracking tells you what happened; a budget tells you what comes next
Tracking is a record of past spending. Budgeting uses that record to make a realistic plan for the next pay period. Begin with a month of transactions, group them into a few useful categories, and compare the total with take-home income. A category is useful when it helps you make a decision, not just when it looks tidy.
Avoid double-counting. If you record a card purchase as spending, paying that card bill later is repayment of the same purchase, not a second expense. Transfers between your own accounts also do not create new income or spending; interest and fees are separate costs. Review your plan against actual spending and adjust it rather than treating the first draft as a test you passed or failed.
Plan for annual bills and uneven paydays
Predictable but irregular expenses need a place in your monthly plan. A sinking fund is money set aside for a known future cost, such as an insurance renewal, a replacement appliance or gifts. Divide the expected cost by the number of months until it is due, and keep that amount separate from emergency savings.
A positive monthly total can still hide a timing problem if rent is due before payday. Put income dates and major bill dates on a calendar, then keep enough in the bill-paying account to bridge the gap. With variable income, base essential commitments on a conservative estimate rather than your best month, and decide in advance where higher-income months will go.
Example: a $4,000 monthly take-home budget
- Needs (50%): $2,000 - rent $1,350, utilities $150, groceries $350, transport $150
- Wants (30%): $1,200 - dining $300, subscriptions $60, shopping and fun $840
- Savings and debt (20%): $800 - emergency fund $500, extra card payment $300
Hypothetical numbers for illustration.
Common mistakes
- Budgeting from gross salary instead of take-home pay.
- Forgetting irregular costs like annual renewals, car repairs and gifts.
- Making the budget so strict that it is abandoned after a month.
- Treating every want as a failure instead of a planned choice.
Key takeaways
- Start with take-home pay and last month's real spending.
- Label costs as needs or wants so you know what can flex.
- Use 50/30/20 as a starting shape, then adjust it to your life.
- Review recurring charges regularly - they are the easiest savings.
How MoneyPatrol can help
MoneyPatrol brings your linked accounts into one view, categorizes spending, and highlights recurring charges so you can see your real cash flow without building a spreadsheet.
For educational purposes only. Not financial, tax, or legal advice. See our full disclaimer.